
Treasury Bill Bond Ladder Etfs
Target-Maturity Municipal Bond Ladders (iBonds IBMM-IBMP & BulletShares): 10-Year Par Call & YTW Math
Direct retail municipal ladders under $500,000 lose 100 to 220 bps to MSRB odd-lot spreads & cluster idiosyncratic local credit risk: defined-maturity AMT-free Municipal iBonds & BulletShares ETFs deliver 400+ bond diversification at 0.18% ER.
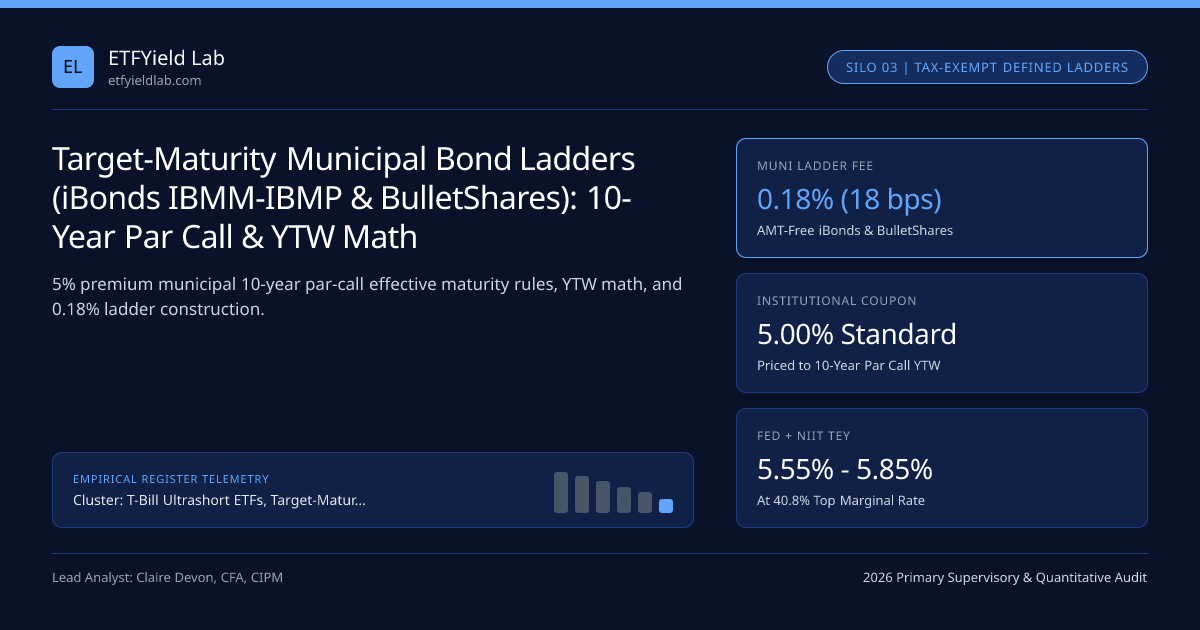
Building a direct $200,000 individual municipal bond ladder in a retail brokerage account is one of the most punishing microstructure traps in personal finance: buying eight $25,000 odd-lot serial bonds surrenders 110 to 220 bps in MSRB EMMA dealer markups, exposes 12.5% of your net worth to any single hospital or water authority downgrade, and traps you with complex 10-year par-call calculations. Combining Tax-Exempt Municipal Bond ETFs (2026 Benchmark Standard) with iShares iBonds & Invesco BulletShares Target-Maturity Bond Ladders unlocks 400-to-900-bond institutional AAA/AA diversification per annual rung for 0.18% ER and 2-to-4 bps limit-order spreads!
Within our T-Bill & Bond Ladder Hub and T-Bill & Bond Ladder Master Guide, pair this tax-exempt ladder blueprint with corporate defined-maturity ladders, high-yield target-maturity ladders, and check exact state/federal tax crossovers in our T-Bill vs duration ETF tax-equivalent yield comparator.
The "Effective Maturity" 10-Year Par Call Rule in Municipal Indices#
Open the holdings CSV of a 2029 Municipal Target-Maturity ETF (IBMR or BSMT), and a newcomer does a double-take: alongside serial bonds maturing in 2029, you see 5.00% coupon state general-obligation bonds with legal final maturities of 2038 or 2044! Why? Because institutional muni markets run on 10-Year Par Call Effective Maturity:
Notice Metric #1—why institutional muni funds love 5.00% premium coupons trading at 105.00! If an ETF bought 2.25% coupon munis at 89.00, shareholders would get crushed by 40.8% federal IRC Section 1278 market discount tax! Buying 5.00% coupons at 105.00 and amortizing the 5-point premium down to 100.00 par ensures 100.0% of your YTW return stays federally tax-free!
Yield-to-Worst (YTW) vs Direct Odd-Lot Break-Even Equation#
At what account size does a custom Separately Managed Account (SMA) of direct $100k+ municipal blocks beat an 18-bp target-maturity municipal ETF ladder? Let us solve the exact transaction-cost crossover:
- YETFNetTEY = ( YTWRoundLotIndex - ER0.18% - (SpreadETF / Years) ) / (1 - tFed_40.8%)
- YDirectTEY = ( YTWRoundLotIndex - (MarkupMSRBEntry + HaircutEarlyExit * pExit) / Years ) / (1 - tFed40.8%)
- Worked 5-Year Tax-Exempt Tuition Ladder ($250,000 Across 2027-2031 Rungs, 40.8% Top Fed+NIIT):
- Institutional Round-Lot Index YTW = 3.48%
- 1. 5-Rung iBonds / BulletShares Muni ETF Ladder (18 bps ER, 2.5 bps limit spread):
- Net Tax-Free Yield = 3.48% - 0.18% - 0.005% = 3.295% -> Federal TEY = 5.57%!
- Credit Diversification = ~2,800 distinct municipal bonds across 5 rungs!
- 2. Direct 10-Bond Retail Ladder ($25,000 odd lots; 85 bps MSRB entry markup; 20% chance of early sale @ 120 bps):
- Annualized MSRB Spread Drag = (0.85% + 0.24%) / 3.0avgyrs = -0.363%/yr (TWICE the 18-bp ETF fee!)
- Net Tax-Free Yield = 3.48% - 0.363% = 3.117% -> Federal TEY = 5.27% (-30 bps worse + concentrated risk!)
Test your exact tax-equivalent yield against state-exempt SGOV and Treasury ladders in our T-Bill vs duration ETF tax-equivalent yield comparator, and model call-adjusted duration in our Bond yield & duration calculator.
Comparing Tax-Exempt Municipal Ladder Access Tiers#
Tax-Exempt Ladder Decision Matrix Across Verified Custodians#
Look closely at Metric #3 above—an essential California/New York nuance: because target-maturity municipal ETFs (IBMM–IBMP) are national portfolios (~82% out-of-state bonds taxed by CA at 13.3%), a 32% federal bracket Californian should compare National Muni iBonds against 100% State-Exempt U.S. Treasury iBonds (IBTG–IBTP, 0.07% ER) before buying!
| Taxable Household Profile | Optimal Defined-Maturity Vehicle | Net Fee | Execution & Custody Rail |
|---|---|---|---|
| 35% - 37% Fed + Low/Mod State Tax (TX, FL, WA, IL, PA, CO) | iBonds / BulletShares Muni Ladder (IBOND-TARGET-MAT) | 0.18% | Limit orders 10:15-15:30 ET at Fidelity / Schwab (SIPC) |
24% - 32% Fed + High SALT State (CA 13.3%, NY 10.9%+) | U.S. Treasury iBonds Ladder (IBTG-IBTP) | 0.07% | 100% CA/NY state-exempt; verify in T-Bill/Duration Tax Tool |
| 37% Fed + CA/NY Perpetual Core (No fixed spending date) | Single-State CA/NY Constant Muni ETF (CMF / NYF) or MUB | 0.05% - 0.08% | Compare long-horizon fee in ETF expense calculator |
| $3M+ Ultra-HNW Held-to-Par State Ladder | Direct $250k+ Institutional Round-Lot State GOs | 0.00% ER | Institutional bond desk at Interactive Brokers / SEC MSRB rules |
Pre-Trade Execution Hygiene on Municipal Rungs#
Because outer-year target-maturity municipal rungs (7–10 years out) often display $15M–$60M AUM with 3 to 6 bps screen spreads, never submit market orders—place patient midpoint limit orders between 10:30 ET and 15:00 ET when underlying MSRB municipal dealers are live.
Frequently asked questions
How can a 2030 Target-Maturity Municipal ETF hold bonds whose stated legal maturity is 2042?
Great institutional question! Both S&P AMT-Free Municipal Series (iBonds) and Invesco BulletShares Municipal indices use "Effective Maturity" rules: a premium 5.00% municipal bond maturing in 2042 with an in-the-money 2030 par call at 100.00 is assigned to the 2030 rung because institutional issuers reliably refund/call 5% bonds at year 10!
What happens ("Extension Risk") if municipal yields spike above 5.25% and callable bonds in a 2030 rung are NOT called?
If yields jump above the 5% coupon so issuers skip calling those bonds in 2030, the ETF sells any remaining uncalled longer-maturity bonds in the institutional round-lot market prior to its scheduled 2030 termination—introducing modest extension price sensitivity on the callable subset, which you can check via Option-Adjusted Duration!
Do iBonds and BulletShares Municipal Ladder ETFs hold AMT Private Activity Bonds?
No on the core suites! Both iShares iBonds Dec Term Muni Bond ETFs (tracking S&P AMT-Free Municipal Series Indices) and Invesco BulletShares Municipal Bond ETFs exclude Alternative Minimum Tax (AMT) bonds—keeping Form 1099-DIV Box 13 at 0.0%!
When do target-maturity municipal ETFs mature each year?
Check the exact suite calendar: iShares iBonds Municipal ETFs terminate around December 1-2 (earlier than Dec 15 corporate iBonds, reflecting major Dec 1 municipal coupon/maturity dates!), while Invesco BulletShares Municipal ETFs terminate around December 15.
Publication record
- Published
- November 13, 2026
- Updated
- November 15, 2026
- Author
- Claire Devon, CFA, CIPM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Claire Devon, CFA, CIPM. (2026, November 15). Target-Maturity Municipal Bond Ladders (iBonds IBMM-IBMP & BulletShares): 10-Year Par Call & YTW Math. ETFYield Lab. https://etfyieldlab.com/yield-guides/target-maturity-municipal-bond-ladders-10-year-par-call-ytwRegulatory Directory Cross-Reference
Referenced Institutions & Regulatory Registries
Mentioned Regulated Institutions
Related Treasury Bill Bond Ladder Etfs & Institutional Briefings
Explore Treasury Bill Bond Ladder Etfs Hub (20) →Treasury Bill Bond Ladder Etfs
T-Bill Ultrashort ETFs, Target-Maturity Bullet Ladders & Roll-Down Yield Engineering GuideTreasury Bill Bond Ladder Etfs
High-Yield Target-Maturity Bond Ladders (iBonds IBHF-IBHL & BulletShares): Default Loss Drag vs Stated YTWTreasury Bill Bond Ladder Etfs
Real-Yield TIPS Ladders vs Constant-Maturity ETFs (VTIP vs SCHP & TIP): Breakeven & Floor MathTreasury Bill Bond Ladder Etfs
Zero-Coupon Treasury STRIPS ETFs (EDV & ZROZ) vs 20+ Year Coupon TLT: 25-Year Duration & Convexity MathTreasury Bill Bond Ladder Etfs
Core Aggregate Bond ETFs (AGG & BND) vs Pure Treasury (GOVT): Agency MBS Convexity & Issuance DriftTreasury Bill Bond Ladder Etfs
Agency CMBS ETFs (CMBS) vs Residential Mortgage-Backed ETFs (MBB & VMBS): Lockout Call Protection & OAS MathTreasury Bill Bond Ladder Etfs
Ultrashort Active Corporate & Commercial Paper ETFs (JPST, MINT & ICSH) vs Pure T-Bill ETFs: SALT Tax AuditTreasury Bill Bond Ladder Etfs
10-Year Bond Ladder Redington Immunization: Matching DV01 Duration, Dispersion & Dated Cash LiabilitiesCovered Call Buffer Option Etfs
SEC Rule 18f-4 Derivatives Risk Management in Option ETFs: 200% Relative VaR & Stress DisclosuresCovered Call Buffer Option Etfs
Laddered 4-Quarter Buffer ETFs (BUFR & FBUF) vs Single-Outcome Series: Smoothing Reset Path RiskCovered Call Buffer Option Etfs
100% Downside-Protection "Max Buffer" ETFs vs DIY T-Bill + S&P 500 Call Barbell: Fee & Tax ComparisonCovered Call Buffer Option Etfs
Protective Collar & Tail-Risk ETFs (NUSI, SPD & TAIL): Why 25-Delta Put Skew Bleeds Compounding
ETFYield Lab Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.