
SEC Yield Distribution Tax Drag
Municipal Bond ETF Tax-Equivalent Yield, 3.8% NIIT Exemption & AMT Private Activity Bond Math
National tax-exempt municipal bond ETFs (MUB, VTEB) escape both the 37% top federal bracket and the 3.8% Net Investment Income Tax—pushing 3.36% tax-free SEC yield to a 5.68% federal Tax-Equivalent Yield, provided investors screen out Alternative Minimum Tax Private Activity Bonds.
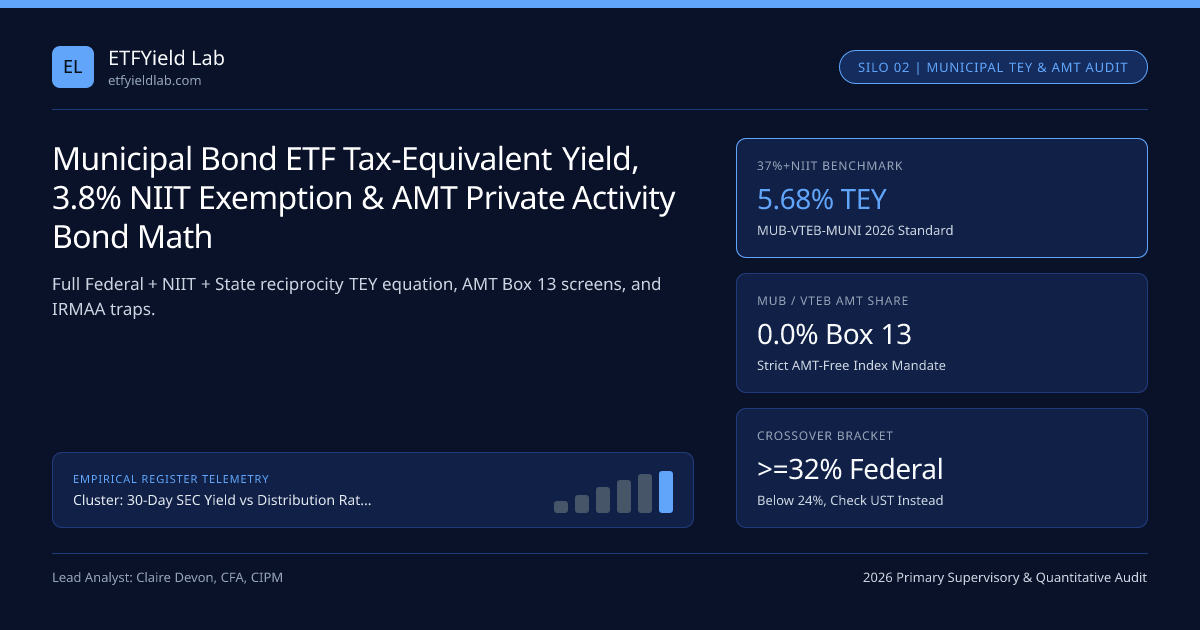
When high-earning physicians, partners, and founders cross the $250,000 married ($200,000 single) Net Investment Income Tax threshold, every dollar of taxable corporate bond interest gets hit simultaneously by up to 37.0% federal income tax, 3.8% IRC Section 1411 NIIT, and 5% to 14.8% state/city tax. Tracked under our Tax-Exempt Municipal Bond ETFs (MUB & VTEB) and 2026 Benchmark Standard, investment-grade municipal ETFs legally eliminate the entire 40.8% federal + NIIT bite—transforming a modest-looking 3.36% SEC yield into a 5.68% federal Tax-Equivalent Yield (TEY) before counting in-state exemptions!
Within our 30-Day SEC Yield & Tax Drag Hub and 30-Day SEC Yield vs Distribution Rate Guide, computing exact Out-of-State Leakage, AMT Box 13 Exposure, and Muni-vs-Treasury Crossover Ratios ensures you never buy munis in the wrong tax bracket.
Exact Federal + NIIT + State Municipal Tax-Equivalent Yield Formula#
In a national municipal ETF (MUB or VTEB), let $p{ ext{home}}$ denote the percentage of exempt interest derived from bonds issued in your home state (plus U.S. territories Puerto Rico, Guam, and U.S. Virgin Islands, which are triple-tax-exempt nationwide!). A single-state ETF (CMF / VCAIX for California; NYF for New York) sets $p{ ext{home}} approx 1.00$:
- EffectiveMuniTaxDrag = (1 - phome) * t_State [Assumes SALT $10k cap already maxed]
- YMuniAfterTax = YSECMuni * (1 - EffectiveMuniTaxDrag) - (pAMT * tAMTEff)
- TEYCorporateEquiv = YMuniAfterTax / (1 - tFed - tNIIT - t_State)
- Exact Muni-to-Treasury Breakeven Yield Ratio (Same State, Zero Credit Spread Adjustment):
- RatioBreakeven (YMuni / YUST) = (1 - tFed - tNIIT) / [ 1 - (1 - phome) * t_State ]
- Worked California Resident Comparison (37% Fed + 3.8% NIIT + 13.3% CA Tax = 54.1% Combined!):
- Option 1: National MUB ETF (3.36% SEC Yield, p_home = 17.5% CA bonds, 0% AMT):
- CA State Tax Bite = (1 - 0.175) * 13.3% = 10.97% -> Net Yield = 3.36% * (1 - 0.1097) = 2.99%
- Corporate Bond TEY = 2.99% / (1 - 0.541) = 6.52% Taxable Corporate Equivalent!
- Option 2: California-Only Muni ETF CMF/PWZ (3.28% SEC Yield, p_home = 100% CA, 0% AMT):
- CA State Tax Bite = 0.00% -> Net Yield = 3.28%
- Corporate Bond TEY = 3.28% / (1 - 0.541) = 7.15% Taxable Corporate Equivalent (+63 bps over MUB!)
Plug your exact federal and state rates into our T-Bill vs duration ETF tax-equivalent yield comparator to test whether national MUB, single-state muni ETFs, or state-exempt SGOV (state-tax U.S. government obligation thresholds) wins at your specific horizon, and model call-adjusted duration in our Bond yield & duration calculator.
Three Hidden Tax Traps Inside Municipal Bond ETFs#
Pay special attention to Gate 2 (IRC Section 1278 De Minimis Market Discount)—a sister rule to IRC Section 1276 market discount in taxable bond ETFs! Unlike par-or-premium 5.00% institutional muni coupons (trading at 104-109), low 2.00% municipal bonds trading at 82.00 violate the 0.25% per year de minimis threshold, turning their entire 18-point pull-to-par gain into fully taxable 37% ordinary income! That is why institutional muni indices weight heavily toward 5% coupon premium structures appraised on Yield-to-Worst (YTW) to their 10-year par call date.
Tax-Equivalent Yield Ladder Across Federal Tax Brackets#
Municipal ETF Selection Across Verified Custodians#
| Municipal Wrapper | Expense Ratio | AMT Exposure | Best Tax Resident Profile | Custody & Tool Link |
|---|---|---|---|---|
| National Core (MUB-VTEB Standard) | 0.05% | 0.0% | 32%-37% Fed in TX, FL, WA, IL, PA, or diversified states | Fidelity / Schwab (SIPC) |
| Single-State CA / NY Muni ETF | 0.07% - 0.15% | 0.0% - 2.0% | 35%-37% Fed domiciled in CA (13.3%) or NY (10.9%+) | Compare net fee in ETF expense calculator |
| Target-Maturity Muni (IBOND-TARGET-MAT) | 0.18% | 0.0% | Defined-date tuition/tax liabilities without MSRB odd-lot haircuts | E*TRADE / Interactive Brokers |
High-Yield Muni ETF (HYD / SHYD) | 0.25% - 0.35% | 14% - 22% Box 13! | Top-bracket non-AMT filers seeking credit spread pickup | Verify SEC Form N-CSR Box 13 history |
Retiree Medicare IRMAA Warning#
One final retirement planning check before shifting $1,000,000 from equity growth into MUB: because IRS Form 1040 Line 2a (Tax-Exempt Interest) flows directly into Medicare IRMAA MAGI, crossing a single $1 IRMAA cliff triggers $1,600 to $9,000+ in annual Part B/D premium surcharges two years later (T+2 lookback). Model IRMAA thresholds before executing large muni conversions near cliff boundaries!
Frequently asked questions
Are municipal bond ETF dividends exempt from the 3.8% Net Investment Income Tax (NIIT) and IRMAA?
Municipal exempt-interest dividends are 100% excluded from the 3.8% Net Investment Income Tax under IRC Section 1411! Caution for retirees, however: Box 12 tax-exempt interest IS added back into Modified Adjusted Gross Income (MAGI) when computing Medicare Part B/D IRMAA surcharges and Social Security taxation!
How are out-of-state municipal bonds inside MUB or VTEB taxed by my home state?
In states with income taxes (such as CA, NY, NJ, MA), only the small fraction of MUB/VTEB earned from bonds issued inside your own home state (e.g., ~17% CA, ~16% NY) is state-tax-free; the ~83% out-of-state municipal interest is taxed at your state rate (though deductible in Utah/Indiana reciprocity rules).
What is Form 1099-DIV Box 13 (Specified Private Activity Bond Interest)?
Box 13 reports interest from qualified private activity municipal bonds (airports, ports, private non-profit hospitals/housing). Taxpayers subject to the federal Alternative Minimum Tax (AMT) must add Box 13 back as an AMT preference item on Form 6251, whereas MUB and VTEB track AMT-free benchmarks.
At what federal income tax bracket do municipal bond ETFs beat U.S. Treasury ETFs?
Historically, when the 10-Year AAA Muni-to-Treasury Yield Ratio sits near 65%-72%, municipal ETFs beat Treasuries at the 32%, 35%, and 37% (+3.8% NIIT) brackets, while 12%, 22%, and often 24% bracket households earn higher after-tax yield in state-exempt U.S. Treasury ETFs!
Publication record
- Published
- November 13, 2026
- Updated
- November 15, 2026
- Author
- Claire Devon, CFA, CIPM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Claire Devon, CFA, CIPM. (2026, November 15). Municipal Bond ETF Tax-Equivalent Yield, 3.8% NIIT Exemption & AMT Private Activity Bond Math. ETFYield Lab. https://etfyieldlab.com/yield-guides/municipal-bond-etf-tax-equivalent-yield-niit-amt-pab-mathRegulatory Directory Cross-Reference
Referenced Institutions & Regulatory Registries
Mentioned Regulated Institutions
Related SEC Yield Distribution Tax Drag & Institutional Briefings
Explore SEC Yield Distribution Tax Drag Hub (20) →SEC Yield Distribution Tax Drag
30-Day SEC Yield vs Distribution Rate, Return of Capital & After-Tax ETF Yield Drag GuideSEC Yield Distribution Tax Drag
TIPS Original Issue Discount (OID) Phantom Tax vs Monthly TIPS ETF Cash DistributionsSEC Yield Distribution Tax Drag
Ex-Dividend Date NAV Drop & The 61-Day QDI Holding-Period Trap: Why Dividend Capture FailsSEC Yield Distribution Tax Drag
IRC Section 1091 Wash-Sale Rules & "Substantially Identical" Bond ETF Tax-Loss Harvesting SwapsSEC Yield Distribution Tax Drag
Contractual vs Voluntary ETF Expense Ratio Fee Waivers: Auditing Subsidized SEC Yield CliffsSEC Yield Distribution Tax Drag
Acquired Fund Fees and Expenses (AFFE) in BDC, CEF & Multi-Asset ETFs: SEC Item 3 Optical RulesSEC Yield Distribution Tax Drag
UK HMRC Offshore Reporting Fund Status & Excess Reportable Income (ERI) on Accumulating UCITS ETFsSEC Yield Distribution Tax Drag
Foreign Tax Credit Pass-Through (IRC Section 853 & Form 1116) in International Dividend & Bond ETFsTreasury Bill Bond Ladder Etfs
High-Yield Target-Maturity Bond Ladders (iBonds IBHF-IBHL & BulletShares): Default Loss Drag vs Stated YTWTreasury Bill Bond Ladder Etfs
Real-Yield TIPS Ladders vs Constant-Maturity ETFs (VTIP vs SCHP & TIP): Breakeven & Floor MathTreasury Bill Bond Ladder Etfs
Zero-Coupon Treasury STRIPS ETFs (EDV & ZROZ) vs 20+ Year Coupon TLT: 25-Year Duration & Convexity MathTreasury Bill Bond Ladder Etfs
Core Aggregate Bond ETFs (AGG & BND) vs Pure Treasury (GOVT): Agency MBS Convexity & Issuance Drift
ETFYield Lab Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.