
Dividend Growth Credit Income Etfs
Convertible Bond ETFs (CWB & ICVT): Asymmetric Equity Delta Participation & Credit Bond Floors
Convertible corporate bonds combine a senior/subordinated fixed-income "Bond Floor" with a free embedded equity warrant: targeting the "Balanced Delta Sweet Spot" inside iShares ICVT (0.20% ER) or SPDR CWB (0.40% ER) captures ~70% of growth-stock upside with ~45% of equity downside!
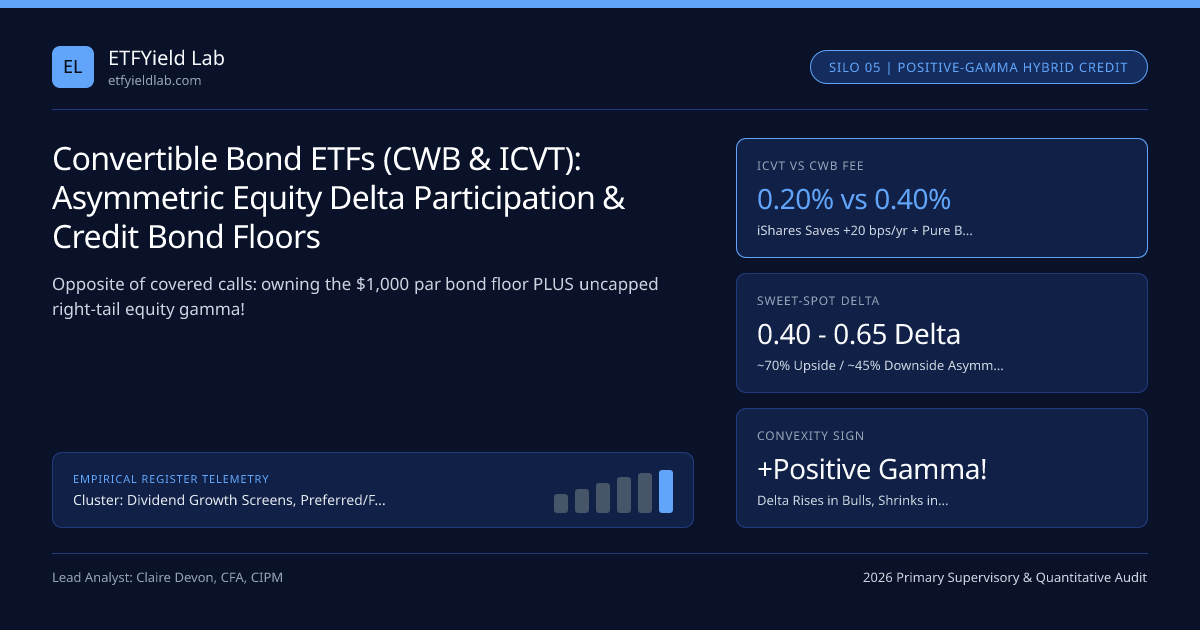
In Silo 04, we saw that Covered-Call ETFs are short equity gamma—capping bull-market upside while absorbing full equity crashes. Convertible Bond ETFs (ICVT at 0.20% ER and CWB at 0.40% ER) are the exact mathematical mirror image: you own a senior/subordinated $1,000-par corporate bond floor PLUS a long 5-year call option on growth equities! As stocks surge, your equity delta automatically expands toward 0.85; as stocks crash, your equity delta shrinks toward 0.15 and the Investment-Value Bond Floor catches your principal!
Inside our Dividend Growth & Credit Income Hub and Dividend & Credit Master Guide, contrast positive-gamma convertibles against IG corporate bonds (LQD/VCIT), Fallen-Angel BB credit (FALN/ANGL), and Silo 04 covered-call caps.
Inside the Convertible Payoff Curve: Bond Floor + Embedded Equity Call#
Trace how a $1,000 par Convertible Bond behaves across the three Equity Delta Zones—and notice why ICVT (0.20% ER, pure convertible bonds) structurally beats CWB (0.40% ER, includes mandatory preferreds lacking a par floor):
Read Metric #4 carefully: Mandatory Convertibles (roughly 10%–12% of CWB, 0% of ICVT) force conversion into depreciated stock at maturity even if the stock dropped -50%—meaning they have NO $1,000 par bond floor! Paying half the fee (0.20% vs 0.40%) in iShares ICVT gets you 100% true par-floored convertible bonds!
Convertible Pricing & Asymmetric Upside/Downside Equation#
Decompose the market price $P{ ext{Conv}}$ of a convertible bond into its **Straight Credit Bond Floor ($B{ ext{Floor}}$) plus its Embedded Call Warrant, and inspect how Positive Gamma ($Gamma > 0$)** protects capital:
- ConversionValue = NConversionRatio * SStock_Price
- BondFloorValue = Sum{t=1..T} [ Coupon / (1 + rUST + OASCredit)^t ] + [ $1,000 / (1 + rUST + OAS)^T ]
- PConvertible = Max( BondFloorValue, ConversionValue ) + TimeValueOption(IV_Stock, Gamma)
- Worked +/- 35% Underlying Growth-Stock Shock on a Balanced Convertible ($1,000 Par, P_0 = $1,040, Bond Floor = $885, Delta = 0.52):
- 1. Underlying Growth Basket Surges +35% (Conversion Value jumps from $860 to $1,161):
- Delta expands from 0.52 -> 0.74 -> P_Convertible rises to ~$1,278 (+22.9% Gain + 2.5% Coupon = +25.4% -> 73% Upside Capture!)
- 2. Underlying Growth Basket Crashes -35% (Conversion Value plunges to $559):
- Bond Floor at $885 ARRESTS the drop! -> P_Convertible stops at ~$905 (-13.0% + 2.5% Coupon = -10.5% -> ONLY 30% Downside Capture!)
Compare 0.20% ICVT vs 0.40% CWB (and 0.85%+ active convertible mutual funds!) in our ETF expense ratio calculator, and model straight-bond floor sensitivity in our Bond yield & duration calculator.
Comparing Hybrid Equity-Credit Vehicles Over Full Cycles#
Look at Metric #3: because SCHD and VYM hold <8% Technology, adding a 10% sleeve of ICVT (0.20% ER) inside your Roth IRA injects bond-floored mid-cap tech/AI/biotech upside without taking unhedged 50x P/E equity drawdown risk!
Convertible Allocation Matrix Across Verified Custodians#
| Portfolio Objective | Optimal Convertible / Credit Choice | Net Fee (ER) | Account Location & Custody Rail |
|---|---|---|---|
Core Buy-and-Hold Convertible Sleeve (5%–10%) | iShares Convertible Bond ETF (ICVT) | 0.20% | Hold inside Roth / Traditional IRA at Fidelity / Schwab (SIPC) |
| Tactical Post-Tech-Crash "Busted Convertible" Trade | ICVT (0.20%) when average bond price sits 85–95 | 0.20% | Captures 5%+ pull-to-par YTM + free equity call at IBKR! |
| Higher Current Coupon Income in IRA | Pair 50% ICVT + 50% FALN / USHY | 0.14% - 0.23% | Blends growth gamma + 6.8% BB cash coupon (SEC) |
| Senior Investment-Grade Bond Floor | Pair w/ VCIT / LQD (0.04%) | 0.04% | Model blended duration in Bond duration calc |
Tactical Delta-Monitoring Rule#
Check ICVT’s monthly Portfolio Average Price before sizing: when average convertible bond price trades between $90 and $108 per $100 par, your downside bond floor is close and tightly protective; if a euphoric tech bubble pushes average convertible prices above $135, trim gains back to target weight before the floor falls 25% below spot!
Frequently asked questions
Why did Convertible Bond ETFs (CWB and ICVT) surge +45% to +53% in 2020 and then drop -20% in 2022?
Delta drift! In 2020, booming cloud, EV (Tesla), and biotech stocks drove CWB/ICVT’s average portfolio equity delta above 0.78—making the ETF behave like an uncapped tech fund on the way up, and then exposing it to a -20% drop from elevated equity premiums in early 2022 before hitting its ~85-cent straight-bond floor!
Why do over 50% of U.S. Convertible Bonds carry "Not Rated" (NR) status from Moody’s and S&P?
Fast Rule 144A institutional execution! High-growth tech and healthcare CFOs with low net debt routinely issue $500M+ convertible notes overnight to institutional QIB desks under SEC Rule 144A without waiting weeks or paying fees for Moody’s/S&P ratings—NOT because they are distressed CCC credits!
What is the difference between iShares ICVT (0.20% ER) and SPDR CWB (0.40% ER)?
Both track Bloomberg U.S. Cash Pay Convertible indices! Minor nuance: CWB includes ~10%-12% Mandatory Convertibles (preferred shares that MUST convert into stock at maturity—higher yield, zero $1,000 par bond floor!), whereas ICVT focuses strictly on true Cash-Pay Convertible Bonds WITH $1,000 par maturity floors at HALF the fee (0.20% ER)!
How are Convertible Bond ETFs taxed—and should they sit in a Taxable account or IRA?
Hold ICVT or CWB inside a Traditional or Roth IRA! Convertible bond coupons are 0% QDI ordinary interest (plus market-discount/OID rules), AND rebalancing appreciated in-the-money convertibles can trigger capital gain distributions—all sheltered at 0% tax inside an IRA!
Publication record
- Published
- November 12, 2026
- Updated
- November 14, 2026
- Author
- Claire Devon, CFA, CIPM
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Claire Devon, CFA, CIPM. (2026, November 15). Convertible Bond ETFs (CWB & ICVT): Asymmetric Equity Delta Participation & Credit Bond Floors. ETFYield Lab. https://etfyieldlab.com/yield-guides/convertible-bond-etfs-cwb-icvt-equity-delta-bond-floorsRegulatory Directory Cross-Reference
Referenced Institutions & Regulatory Registries
Mentioned Regulated Institutions
Related Dividend Growth Credit Income Etfs & Institutional Briefings
Explore Dividend Growth Credit Income Etfs Hub (20) →Dividend Growth Credit Income Etfs
Dividend Growth Screens, Preferred/Fallen-Angel Credit ETFs & Securities Lending Master GuideDividend Growth Credit Income Etfs
Emerging Market Debt ETFs: USD Sovereign (EMB & VWOB) Duration vs Local-Currency (EMLC) FX CarryDividend Growth Credit Income Etfs
Total Shareholder Yield ETFs (SYLD & DIVB): Combining Cash Dividends, Net Buybacks & Debt PaydownDividend Growth Credit Income Etfs
International Developed Dividend ETFs (SCHY, VYMI & IDV): FCF Screens, Foreign Tax Credits & FXDividend Growth Credit Income Etfs
Taxable vs Roth/Traditional IRA DRIP Compounding Math: Tax-Lot Hygiene & Yield-on-Cost MythsDividend Growth Credit Income Etfs
Investment-Grade Corporate Bond ETFs (LQD, VCIT & VCSH): BBB Cliff Risk, OAS & Duration DriftDividend Growth Credit Income Etfs
High-Yield Corporate Bond ETFs (HYG, JNK & USHY): Default- & Recovery-Adjusted Net Credit CarryDividend Growth Credit Income Etfs
The BB/BBB Credit Crossover Anomaly: Duration-Times-Spread (DTS) Risk Parity & Sharpe OptimizationBroker Fees and Calculators
BlackRock Bitcoin ETF outflows hit $1.66B over seven trading sessionsDividend Announcements
NRG Energy declares $0.475 dividendMarket Insights
Think the bond market is broken? History says a massive turnaround could be coming.Market Insights
Goldman says 'the pieces are in place' for a shift in Treasury yields, global 10-years
ETFYield Lab Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.